


How higher earners can reduce their tax burden through a VCT

THIS SCENARIO IS FOR ILLUSTRATIVE PURPOSES ONLY
Our Venture Capital Trust (VCT) planning scenarios are based on situations advisers often encounter, making them a great starting point for discussions with your own clients.
Pensions remain the most tax-efficient way to invest for retirement, but they may not always be the right investment option for your clients. Even high-earning clients can still find themselves facing financial challenges, or with liquidity needs in the not-too-distant future. Many of your clients may welcome a tax-efficient investment alternative that doesn’t involve tying up their wealth until they reach retirement age.
Meet Reuben
In this client planning example, Reuben is a 42-year-old Finance Director with an annual salary of £150,000. Reuben recently received an annual bonus of £50,000 and considered paying a lump sum into his pension. While he recognises this may be the most tax-efficient option, he knows he won’t be able to access this money until he’s 57 or older. He would prefer not to tie up his money for that long.
How higher rate taxpayers benefit from owning a VCT
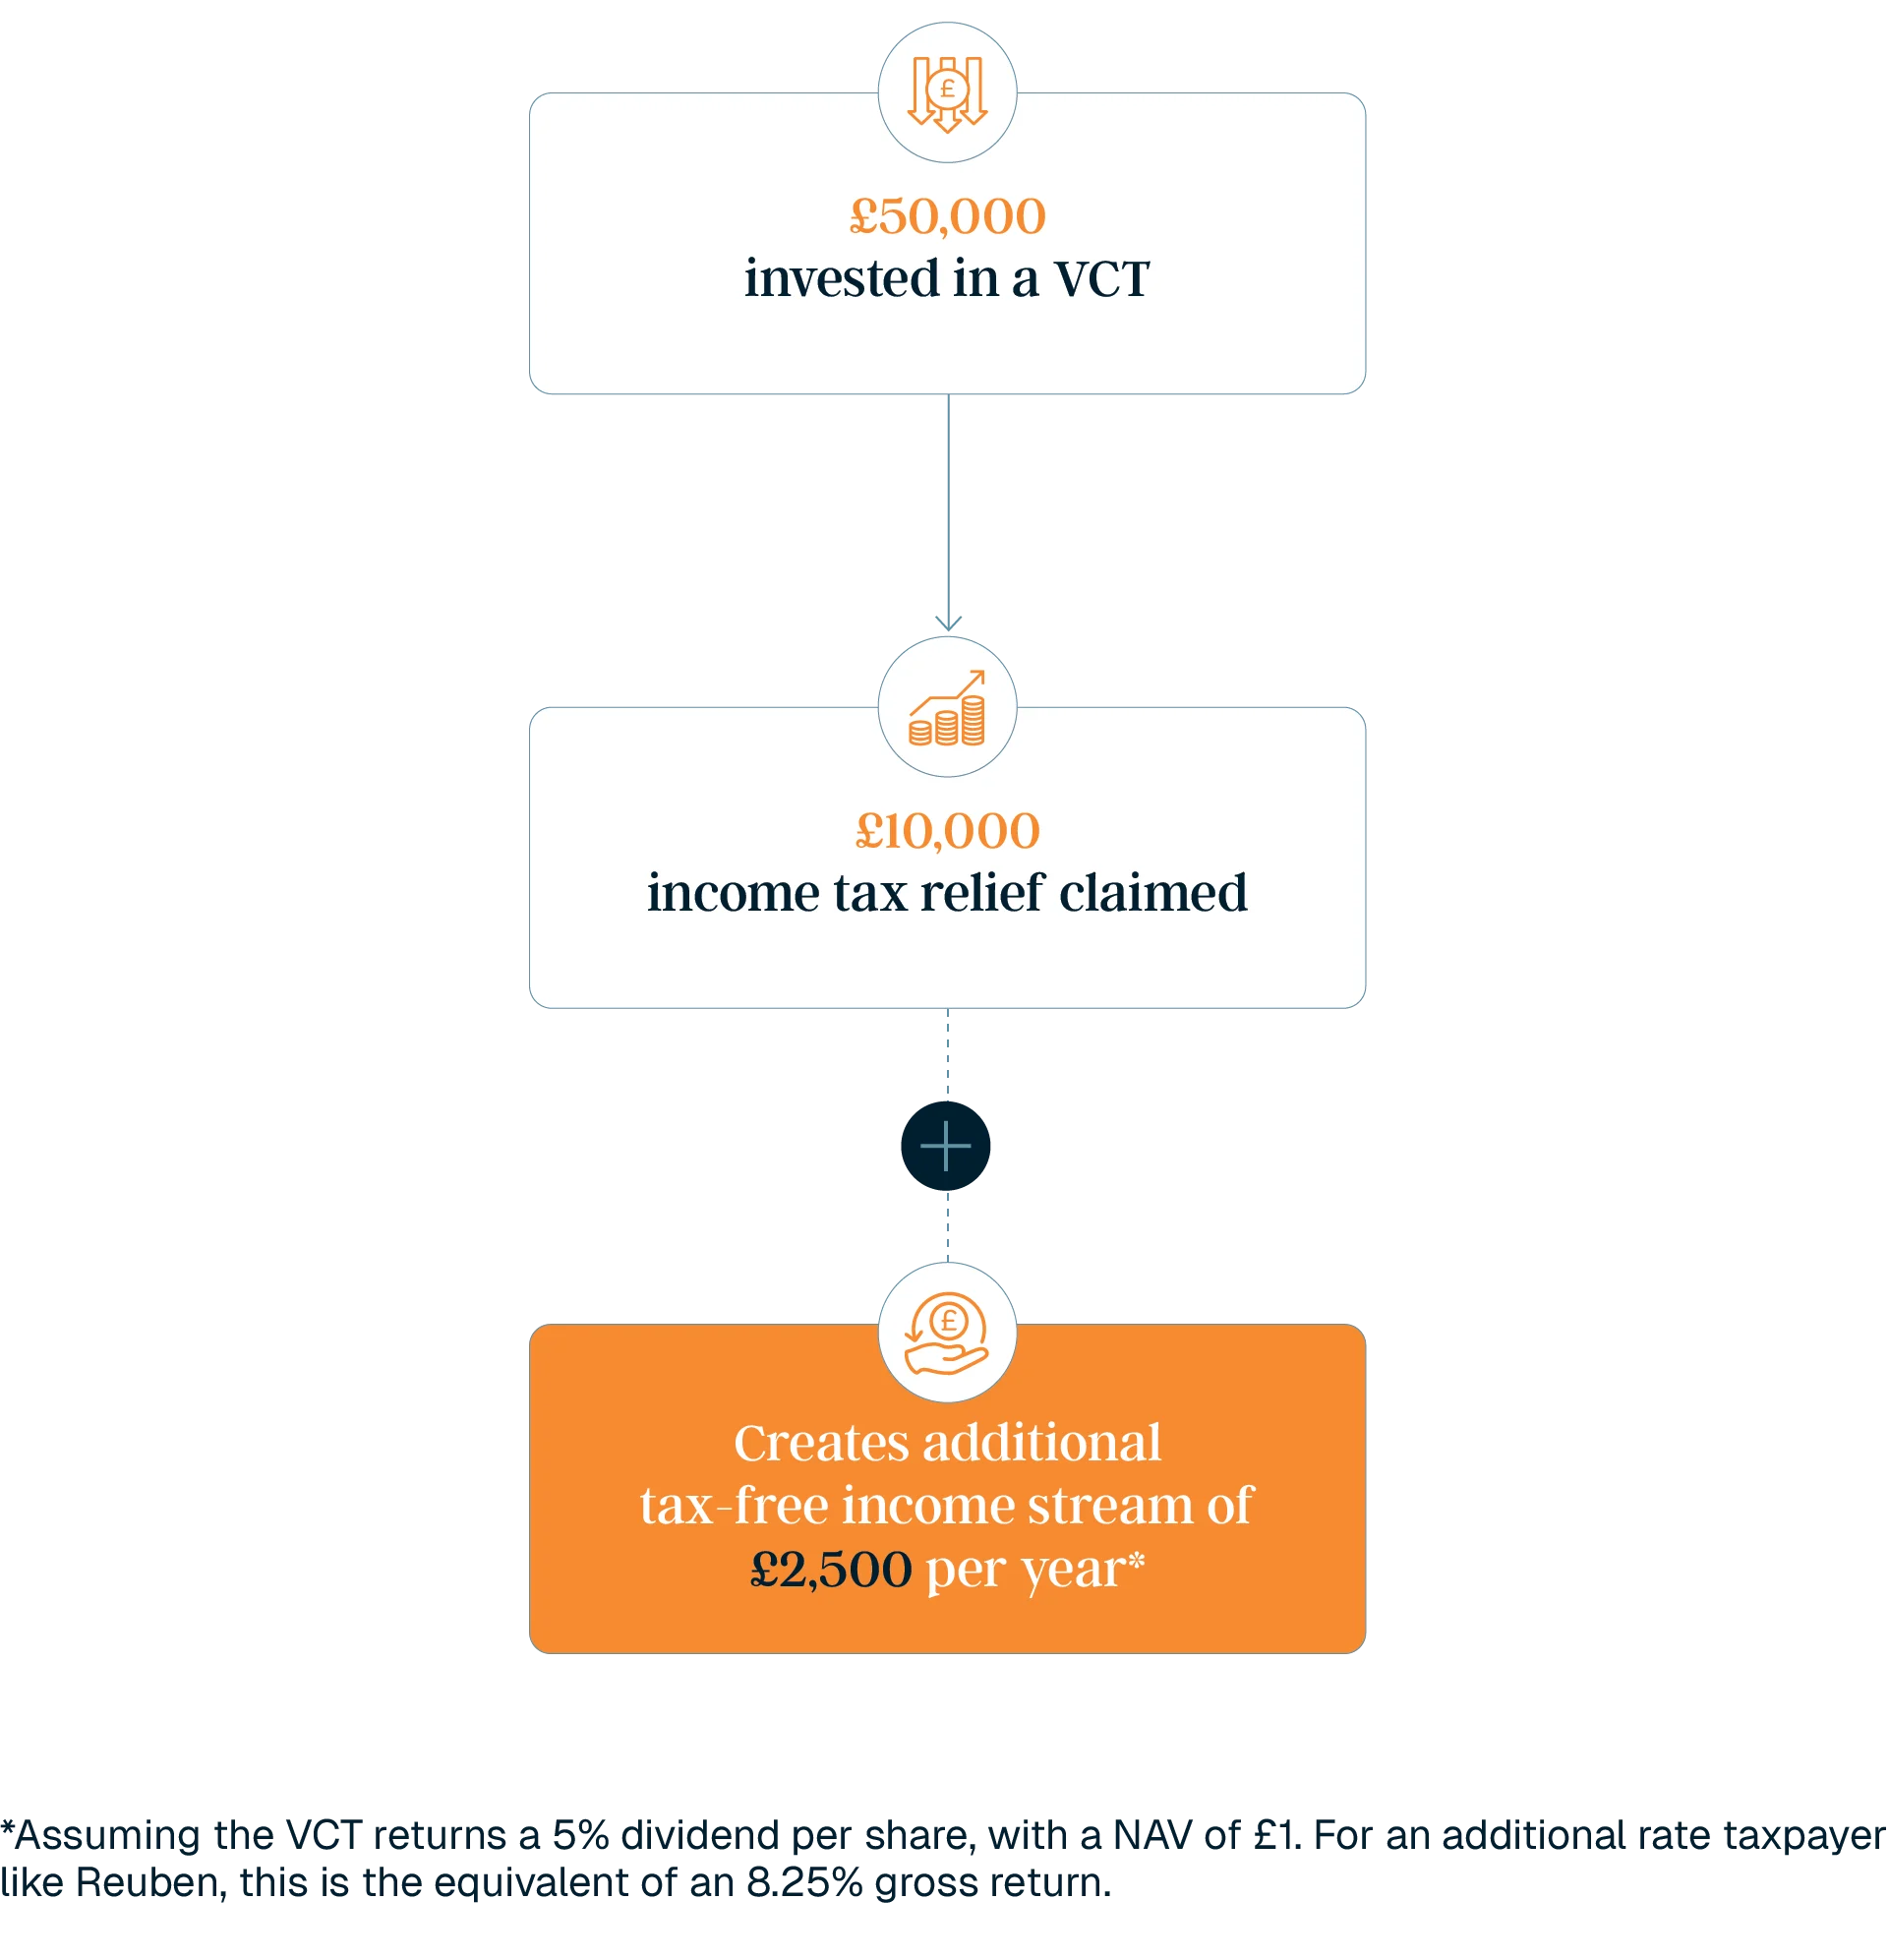
Reuben’s financial adviser talks through the benefits and the risks of investing in a VCT. The adviser explains that if Reuben invested £50,000 into a VCT, he could claim up to 20% upfront income tax relief on the investment, equalling £10,000, provided he holds his VCT shares for the minimum of five years.
As most VCTs target a dividend, Reuben can also expect to receive an annual tax-free income from his investment. Dividends from a VCT are always subject to performance at the discretion of the Board. VCT dividends are completely tax-free and there’s no HMRC requirement to declare them on his tax returns. And with the dividend allowance cut to just £500 since April 2024, tax-free VCT dividends could be especially appealing for high earners like Reuben. For example, an additional-rate taxpayer would need over 9% gross income from an investment to match a 5% tax-free VCT yield.
Investor’s capital is at risk. This illustration does not take into account investment growth or charges for the investment. It is based on tax rules and personal allowances at April 2026, which could be subject to change and depend on individual circumstances. Tax reliefs depend on a VCT maintaining its qualifying status and target returns may not be guaranteed.
Related Scenarios


